

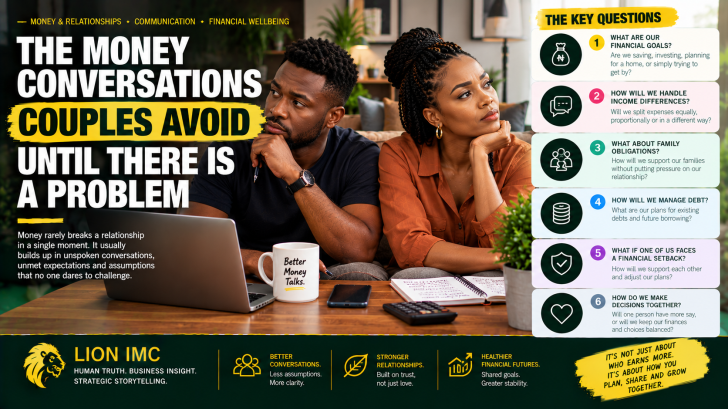
Debt, family obligations, secret savings, spending habits and the future: the conversations that feel uncomfortable before marriage can become much harder when rent is due, income falls or trust is broken.
A couple can discuss wedding colours, the guest list, where to live and how many children they hope to have without ever having an honest conversation about money.
They may know each other’s favourite meals, family histories and career ambitions. They may even know how much each other earns.
But do they know how much the other owes? What financial responsibilities come with their families? Whether one partner expects to support the other indefinitely? Or what would happen if one of them lost their job tomorrow?
These are not necessarily questions people avoid because they are dishonest. Sometimes they are afraid of appearing materialistic. Sometimes they do not want to spoil a happy moment. Sometimes they assume that love, trust and common sense will help them figure everything out later.
And sometimes they simply do not know how to begin.
Research published in the Journal of Consumer Psychology examined financial communication across eight studies involving 8,474 participants. It found that people experiencing greater financial stress were less willing to discuss money with their partners when they anticipated conflict. When conflict seemed more solvable, that reluctance weakened. The findings help explain why the people who most need to talk about money may also be the people most tempted to avoid it.
The problem is that money does not wait for a convenient moment.
The bill arrives. A family member needs help. A loan repayment is due. One partner discovers a purchase they did not know about. A job disappears.
Suddenly, a conversation that could have happened calmly months earlier must take place under pressure.
The most important money conversations in a relationship are often the ones that seem unnecessary while everything is going well.
1. “How much do you actually owe?”
Income is relatively easy to discuss. Debt can feel different.
A partner may be comfortable saying they earn ₦800,000 a month but less comfortable explaining that a substantial part of that income goes towards loan repayments, credit purchases, unpaid bills or money borrowed from friends and relatives.
There may be a car loan, a business loan, salary advances, outstanding school fees or money borrowed to help a family member through an emergency.
The debt may be manageable. The problem is when the other person is making decisions based on an incomplete picture of the household’s finances.
Imagine planning to rent a more expensive apartment together, only to discover that one partner has been using a significant portion of their salary to repay a loan.
The question is no longer simply whether the apartment is affordable. It is whether the couple has been making plans using information that was never fully shared.
Partners do not need to disclose every financial detail on a first date. But as a relationship moves towards marriage, shared property, joint borrowing or major financial commitments, outstanding debts become relevant to decisions that affect both people.
The useful conversation is not, “Why are you in debt?”
It is: “What do we need to understand about our financial obligations before we make our next big decision?”
2. “What do we owe our families?”
For many Nigerian couples, a household budget does not end at the front door.
There may be parents who depend on regular support, younger siblings in school, relatives who need medical assistance or family members who expect financial help when something goes wrong.
Supporting family is not inherently irresponsible. It can be an important expression of love, gratitude and duty.
But the amount, frequency and expectations surrounding that support can become a source of conflict when partners have different assumptions.
One person may believe that sending money to parents every month is non-negotiable. The other may believe that the couple should first build an emergency fund or save towards a home.
Both may have legitimate concerns.
The difficulty arises when one partner’s financial commitments are treated as private matters even though they affect shared goals—or when the other partner assumes that getting married automatically transfers responsibility for every extended-family expense.
These expectations should be discussed explicitly.
How much support can each person afford? Which obligations are regular, and which are emergencies? What happens when a relative requests more than the couple has budgeted? Are both partners expected to contribute to each other’s families?
There is no universal answer. Couples have different incomes, traditions and responsibilities.
But a family obligation that is never discussed can become a household expense that nobody has agreed how to manage.
3. “What does financial security mean to you?”
Two people can earn similar amounts, share a home and still have completely different ideas about money.
One partner may feel secure when there is a substantial amount in savings. The other may believe that money should be invested in property or a business rather than sitting in an account.
One may be cautious about borrowing. The other may consider a loan a reasonable way to acquire an asset.
One may want to save aggressively for retirement. The other may prioritise travel, experiences or helping family members while they are still working.
These differences are not automatically signs of incompatibility. They may reflect different experiences of money, different responsibilities or different ideas about what makes life worthwhile.
The important thing is to understand those differences before they become recurring arguments.
Ask each other:
- What does being financially secure mean to you?
- How much uncertainty are you comfortable with?
- What are we willing to sacrifice to achieve our long-term goals?
- What do we want to enjoy now rather than postpone indefinitely?
- Which financial decisions would make either of us uncomfortable?
The Consumer Financial Protection Bureau identifies personal goals, circumstances and the influence of close relationships as factors that shape people’s financial choices. Understanding these motivations can help make money discussions more meaningful than simply comparing spending habits.
You may discover that you disagree about how to reach your goals but share the same underlying priorities. Or you may discover that your definitions of a good financial life are very different.
Either discovery is more useful before you commit to a major shared expense.
4. “Are we being honest about what we can afford?”
There is a difference between being able to pay for something and being able to afford it comfortably.
A couple may be able to pay for a wedding, holiday, car or apartment by using savings, borrowing money or postponing other plans.
But what happens afterwards?
Will they still have money for emergencies? Will one person quietly struggle to cover everyday expenses? Will the purchase delay a goal that matters more to both of them?
Financial pressure can be particularly difficult when couples feel they must maintain a certain lifestyle to meet family expectations or keep up with friends.
Perhaps the wedding has to be elaborate because relatives expect it. Perhaps a particular neighbourhood seems necessary to demonstrate success. Perhaps one partner wants a holiday that colleagues have been posting about online.
The question becomes whether the couple is choosing a lifestyle that fits their financial reality or trying to maintain an image that their income cannot comfortably support.
This conversation should not become an excuse to shame a partner for wanting nice things. Enjoyment matters too.
But both people should be able to distinguish between a shared priority and an expense one partner feels pressured to accept.
A useful question is:
“If we pay for this now, what will we have to postpone, reduce or give up?”
That question makes the trade-off visible before the money is spent.
5. “What happens if one of us loses an income?”
It is easy to plan a future around the salaries and businesses that exist today.
It is harder to discuss what happens when those income sources disappear.
One partner may lose a job. A business may experience a difficult year. A health problem may interrupt someone’s ability to work. A major client may leave. An industry may change.
These are not predictions that something bad will happen. They are possibilities worth considering when two people are building a life together.
If one income disappears, how long can the household cover essential expenses? Which costs can be reduced? Does either partner have savings that could help? Would the other person be expected to cover everything? For how long?
There is also a more personal question: if one partner becomes temporarily dependent on the other, how will they handle the change?
A couple does not need a perfect financial safety net before discussing these possibilities. In fact, understanding the risks may help them start building one.
The objective is not to eliminate every uncertainty. It is to avoid making the first serious conversation about financial resilience after the crisis has already arrived.
6. “What are we saving for and whose goals come first?”
Couples often say they want to build a future together. But that future may mean different things to each person.
One wants to buy a house. The other wants to start a business.
One wants to save for children’s education. The other wants to support ageing parents.
One wants to invest aggressively. The other wants the comfort of a large emergency reserve.
All these goals may be reasonable. The challenge is that income is finite, and pursuing one goal can delay another.
Without a shared plan, financial decisions can become a competition in which each partner tries to secure money for their own priorities.
A better approach is to make the priorities visible.
Separate essential obligations from important long-term goals and discretionary spending. Agree on what needs attention first, what can happen simultaneously and what must wait.
Some goals will require compromise. Others may be achievable through separate personal savings alongside shared household contributions.
The aim is not to ensure that every preference receives equal funding. It is to make sure that both partners understand the choices being made and have a meaningful opportunity to influence them.
7. “How much financial independence should each of us have?”
Love does not automatically answer the question of how couples should organise their accounts.
Some people prefer to pool all their income. Others maintain separate accounts and contribute to shared expenses. Some use a combination: a joint account for household costs, individual accounts for personal spending and a separate arrangement for savings.
None of these structures is automatically right for every couple.
What matters is whether the arrangement is understood, workable and fair to both people.
If all income goes into one account, who decides how the money is spent? If accounts remain separate, how are shared bills divided? Can either partner make personal purchases without seeking permission? How will large expenses be approved? Does each person understand the household’s overall financial position?
There is another practical issue: both partners should know enough about their shared financial life to manage it if the other person becomes unavailable.
The US Consumer Financial Protection Bureau has highlighted the importance of both partners understanding household income, accounts, assets and financial arrangements rather than leaving all financial knowledge with one person. This is general guidance, not evidence that every Nigerian couple needs joint accounts.
Financial independence and shared responsibility are not necessarily opposites. A couple can preserve individual autonomy while making joint decisions about the commitments they share.
8. “Is there anything about your finances you are afraid to tell me?”
This may be the hardest conversation of all.
Perhaps one partner has been hiding spending. Perhaps a business investment failed. Perhaps money borrowed from a friend has not been repaid. Perhaps one person has been sending more money to family than they previously admitted.
Sometimes the secret involves a serious financial risk. Sometimes it involves embarrassment or fear of being judged.
The conversation matters because financial decisions depend on trust. If one partner discovers that important information has been withheld, the concern may extend beyond the amount of money involved.
Why was it hidden? What other decisions have been made without disclosure? Can the couple still make reliable plans together?
Not every personal purchase requires advance permission, and financial privacy is not automatically dishonesty. Couples should distinguish between maintaining personal autonomy and concealing information that materially affects shared obligations.
If a disclosure reveals a problem, the next step should be to establish the facts, understand the consequences and agree on what needs to change.
A difficult truth shared voluntarily may be painful. A pattern of concealment can make it much harder to rebuild confidence.
How to start the conversation without turning it into an argument
The answer is not to gather every uncomfortable question and present them all during one tense evening.
Choose a calm time. Explain that the goal is to understand each other and plan together, not to investigate or accuse.
Research involving 1,079 newlywed couples found associations between earlier financial discussions, healthier financial communication, marital satisfaction and fewer financial disagreements. The study does not establish a guaranteed formula for every relationship, but it supports the value of addressing money before disagreements become entrenched.
A practical first conversation could follow five steps:
- Start with your own experience. Explain what money meant in your family, what makes you anxious and what financial security looks like to you.
- Share the relevant facts. Discuss income, debts, regular obligations, savings and financial commitments that affect shared plans.
- Listen before trying to solve everything. You may discover that an apparently irresponsible habit reflects a different priority, an obligation you did not know about or a genuine financial difficulty.
- Choose one decision to make together. Start with a budget, an emergency fund, family-support boundaries or a savings target instead of trying to settle every financial question at once.
- Agree to revisit the conversation. Income, responsibilities and goals change. Regular check-ins can help prevent a workable arrangement from becoming outdated.
If conversations repeatedly become hostile, coercive or impossible to resolve, a qualified relationship counsellor or financial professional may help. Where there is financial abuse or a risk to someone’s safety, protecting the affected partner’s access to resources and support takes priority over simply improving communication.
The conversation should happen before the problem
There is no perfect time to discuss money. But there are certainly more and less difficult times.
Before a wedding, you can discuss expectations. Before taking a loan together, you can examine the risks. Before moving house, you can compare what each option would cost. Before a financial crisis, you can agree on what you would do if income changed.
These conversations do not guarantee that a couple will never disagree. They make it less likely that a disagreement will also become a discovery of information that should have been shared earlier.
And the objective is not complete financial transparency without boundaries. Partners are still individuals with legitimate privacy and personal choices.
The goal is to share enough information to make informed decisions about the life they are building together.
THE LION TAKE
Love may bring two people together. But shared financial decisions require more than good intentions. They require honest information, clear expectations and the willingness to discuss uncomfortable realities before those realities become emergencies.
You do not need to agree on every naira. You do need to understand what each of you is bringing into the relationship, what you are trying to build and what happens when the plan changes.
The strongest money conversation is not the one in which nobody disagrees.
It is the one in which both people can tell the truth, ask difficult questions and leave with a clearer understanding of what they will do next.
THE BIG QUESTION
Which money conversation do you think couples should have before marriage but too often postpone until it becomes a problem?