

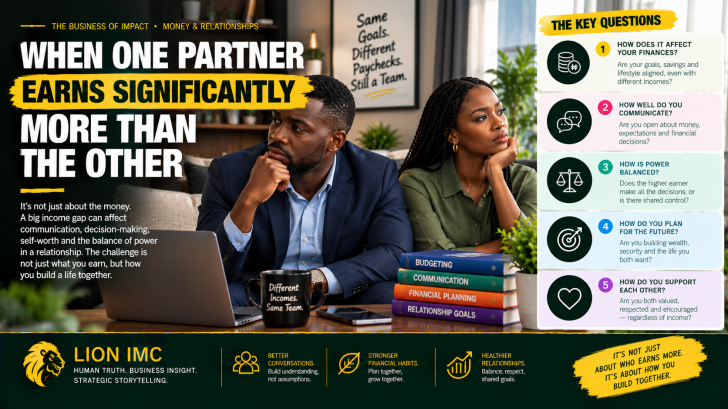
An income gap does not have to become a relationship problem. But when money starts determining whose choices matter, who feels indebted and who gets to decide, the issue becomes much bigger than the payslip.
There is a moment in some relationships when a conversation about money becomes a conversation about worth.
One partner earns ₦2 million a month. The other earns ₦350,000.
They love each other. They share plans for the future. They may even agree on the kind of life they want to build.
But when it is time to pay for a holiday, rent an apartment, buy a car, support a relative or make a major investment, the income difference becomes difficult to ignore.
The higher earner can afford the more expensive option. The lower earner cannot contribute equally without stretching their finances.
Should they split the cost 50–50?
Should each contribute according to income?
Should the person who earns more pay for the bigger things?
And if one partner pays for most of the household’s expenses, does that give them more say in how the household lives?
These questions rarely appear on a couple’s list of romantic milestones. Yet they can shape everyday life in ways that flowers, anniversary dinners and declarations of love cannot resolve.
When one partner earns significantly more than the other, the challenge is not simply how to share the bills. It is how to share a life without turning money into a measure of importance.
The person who earns more may not realise what the difference feels like
Imagine that one partner suggests dinner at an expensive restaurant.
For the higher earner, it is an ordinary Friday evening. The bill is manageable, and the experience seems worth the money.
For the lower earner, the same outing could mean spending money intended for transport, groceries or savings.
Both partners may genuinely want to enjoy the evening. But they are not experiencing the price in the same way.
This difference can appear in housing, holidays, gifts, social activities, childcare, family obligations and long-term plans.
The higher earner may think, “Why are we making such a big deal about this?”
The lower earner may think, “Why does everything we do have to cost this much?”
Neither thought necessarily means the relationship is in trouble. The problem emerges when one partner assumes that what feels affordable to them should feel affordable to the other.
Over time, the lower earner may begin declining invitations, avoiding conversations about money or quietly feeling embarrassed about what they can contribute.
The higher earner, meanwhile, may feel that they are constantly compromising or carrying responsibilities that should be shared.
The income gap is real. But the assumptions surrounding it can create an additional gap in the relationship.
Is a 50–50 split actually fair?
Splitting every bill equally sounds straightforward. Both people pay half, and nobody owes the other anything.
But equal amounts do not always represent equal sacrifices.
Consider this simplified example:
| Monthly income | Partner A | Partner B |
| Net income | ₦2,000,000 | ₦400,000 |
| Half of a ₦600,000 shared expense | ₦300,000 | ₦300,000 |
| Share of individual income used | 15% | 75% |
The same bill consumes 15% of Partner A’s income but 75% of Partner B’s.
Both have paid the same amount. They have not experienced the same financial burden.
This does not mean that every couple must divide expenses in proportion to income. Some couples prefer equal contributions, others pool their earnings, and others maintain separate finances while sharing selected costs.
The important question is whether the arrangement is sustainable and acceptable to both people.
For some couples, a proportional arrangement may be more workable. If one partner earns five times as much as the other, they might agree to contribute more towards shared expenses in line with their respective incomes. They would still need to consider debts, dependants, existing obligations and individual financial goals.
Research on household financial management has found that how couples make financial decisions together is associated with their financial outcomes and experiences of financial difficulty. The evidence does not establish one arrangement as best for every couple, but it reinforces the importance of looking beyond the mere existence of a joint or separate account.
Fairness is not always about contributing the same amount. It is about agreeing on a contribution that recognises the realities of both partners.
When the higher earner becomes the decision-maker
This is where the conversation becomes more complicated.
Suppose the higher-earning partner pays most of the rent, covers the holidays and handles a large share of household expenses.
At first, both people are comfortable with the arrangement.
Then a major decision comes up. One partner wants to move to a more affordable neighbourhood to save towards a business. The other prefers to stay in a more expensive area.
The higher earner says, “I am the one paying for this house.”
The sentence changes the conversation.
The issue is no longer simply where the couple should live. It is whether financial contribution gives one person greater authority over a decision that affects both of them.
The same dynamic can appear when deciding whether to have children, support a relative, change jobs, relocate, buy property or fund a business.
A person who contributes more money may reasonably want their concerns taken seriously, especially when they carry more financial risk. But there is a difference between having a significant stake in a decision and having the final say in everything.
A 2024 study published in Family Relations examined financial conflict, financial deception and unequal influence over financial decisions among couples. The researchers found associations between these factors, relational power and relationship outcomes. The study does not mean that every income difference creates an unhealthy power imbalance; it highlights why financial decisions and relationship dynamics cannot always be separated.
The danger is when financial contribution becomes a standing argument for control.
Paying more towards a shared life does not make one partner more entitled to dignity, respect or a voice in that life.
The lower earner can begin to feel like a dependent
Not every lower-earning partner feels insecure. Some people are comfortable with the difference, confident in their contribution and happy with the arrangement they have negotiated.
But others may struggle with the feeling that they are always receiving more than they can give financially.
Perhaps one partner pays for most dates. Perhaps one buys the furniture, pays for holidays or handles unexpected expenses. Perhaps one can easily provide expensive gifts while the other must save for weeks to buy something modest.
The lower earner may start to feel that their contribution is less meaningful.
They may become reluctant to ask for anything. They may avoid expressing a different opinion because they do not want to seem ungrateful. They may overcompensate by taking on household responsibilities or trying to prove their worth in other ways.
The higher earner may not intend to create this pressure. They may simply be doing what they can afford to do.
But intention does not always determine how an arrangement feels.
A relationship becomes harder to sustain when one person feels permanently indebted and the other feels permanently responsible.
Money can be a practical resource. It should not become a running account of who deserves more affection, influence or consideration.
And what if the woman earns more?
The income difference can carry an additional layer when it challenges the expectations that partners, families or communities have about gender and provision.
A woman who earns significantly more than her male partner may be entirely comfortable with the arrangement. Her partner may be proud of her achievements and secure in their shared life.
In other relationships, the difference may expose assumptions about who should provide, who should lead and what financial contribution says about masculinity or femininity.
The higher-earning woman may feel pressured to minimise her success or reassure her partner. The lower-earning man may feel that his contribution is being judged against an expectation he cannot currently meet.
These are possibilities, not universal truths about Nigerian men or women. Couples differ widely in their values, expectations and arrangements.
The useful question is whether the partners have examined their own expectations or are simply acting out roles they inherited without discussion.
If one partner is uncomfortable with the income difference, pretending it does not matter may not make the discomfort disappear.
Likewise, earning less does not automatically make someone insecure, and earning more does not automatically make someone controlling.
The income gap tells you how much the partners earn. It does not tell you how they respect each other.
What happens when family obligations enter the picture?
In Nigeria, a couple’s financial decisions may extend beyond their immediate household.
There may be parents who need support, siblings paying school fees, relatives facing emergencies, family ceremonies, medical bills or other commitments that neither partner can simply ignore.
Now imagine that one partner earns substantially more and regularly supports their own family.
The lower earner may wonder why the couple cannot save more towards a shared goal. The higher earner may feel that family support is a responsibility they cannot abandon.
Alternatively, the lower earner may be the person with greater family obligations despite earning less.
This is why comparing salaries alone rarely reveals a couple’s actual financial position.
Income is one part of the picture. Existing responsibilities, debt, savings, job security, dependants and future plans matter too.
Partners do not need identical financial circumstances to build a shared future. But they do need enough openness to understand what each person is carrying.
That means discussing family support before it becomes a recurring argument, agreeing on what the household can afford and being honest about the commitments that affect shared goals.
It also means recognising that one partner’s family obligations should not automatically become the other’s financial responsibility without agreement.
So, what should couples actually do?
There is no single financial arrangement that works for every relationship. But couples can reduce the tension by making the rules explicit rather than relying on assumptions.
1. Talk about money before a major decision forces the conversation.
Discuss income, debt, savings, family commitments and financial priorities. Research involving 1,079 newlywed couples found that earlier financial discussions and healthier financial communication were associated with better marital satisfaction and fewer financial disagreements in the study’s analyses. These findings support the value of conversation, although they do not guarantee a particular outcome for every couple.
2. Decide how shared expenses will be divided.
You might choose equal contributions, proportional contributions, a shared account for household expenses or another arrangement that suits your circumstances. The important thing is that both partners understand and accept the system.
3. Agree on what requires a joint decision.
A difference in income does not remove the need to discuss major commitments that affect both partners. Agree on thresholds for significant spending, borrowing, investments and family obligations.
4. Preserve some financial independence where possible.
A shared household does not necessarily require every naira to be pooled. Depending on the couple’s circumstances, personal savings or individual spending money can help each partner retain autonomy. The arrangement should also protect both people from financial secrecy, coercion or one-sided access to essential resources.
5. Recognise contributions that do not appear on a payslip.
Childcare, household management, emotional support, caring for relatives and taking on responsibilities that allow the other partner to pursue their career can all contribute to a shared life. These contributions should not be assumed to cancel out every financial difference, but they should not be treated as worthless simply because they do not generate a salary.
6. Revisit the arrangement as life changes.
A promotion, job loss, business setback, new child, illness or relocation can change what each person can contribute. A financial agreement should be able to adapt without turning a temporary difference into a permanent judgement about someone’s worth.
The real test is what happens when the money is unequal
A couple can have a large income gap and build a healthy partnership.
They can also earn similar amounts and still struggle with control, secrecy, resentment or incompatible financial priorities.
The difference is not simply the size of the gap. It is how the partners respond to it.
Can the higher earner discuss money without using it as leverage?
Can the lower earner express needs and preferences without feeling ashamed?
Can both people disagree about spending without treating the disagreement as proof that one person is ungrateful or irresponsible?
Can they make decisions that reflect their shared future, even when they contribute different amounts?
These questions matter more than whether one person earns twice, three times or five times as much as the other.
The goal is not to pretend the difference does not exist. The goal is to manage it without allowing it to define the relationship.
THE LION TAKE
A healthy partnership does not require two equal payslips. It requires two people who can discuss unequal circumstances without turning them into unequal worth.
One partner may earn more today. The other may earn more tomorrow. One may contribute more money while the other carries responsibilities that are harder to measure. Their circumstances may change many times over the course of a life together.
The strongest arrangement is not necessarily the one where every bill is split down the middle.
It is the one where both people understand the agreement, retain a meaningful voice and can build towards shared goals without one person feeling permanently indebted or the other permanently entitled to control.
Because a relationship is not a competition over who contributes the most.
It is a decision about what two people are trying to build and whether both still have a place in the decisions that shape it.
THE BIG QUESTION
If one partner earns five times as much as the other, should they split shared expenses equally, contribute according to income, or agree on a completely different arrangement?