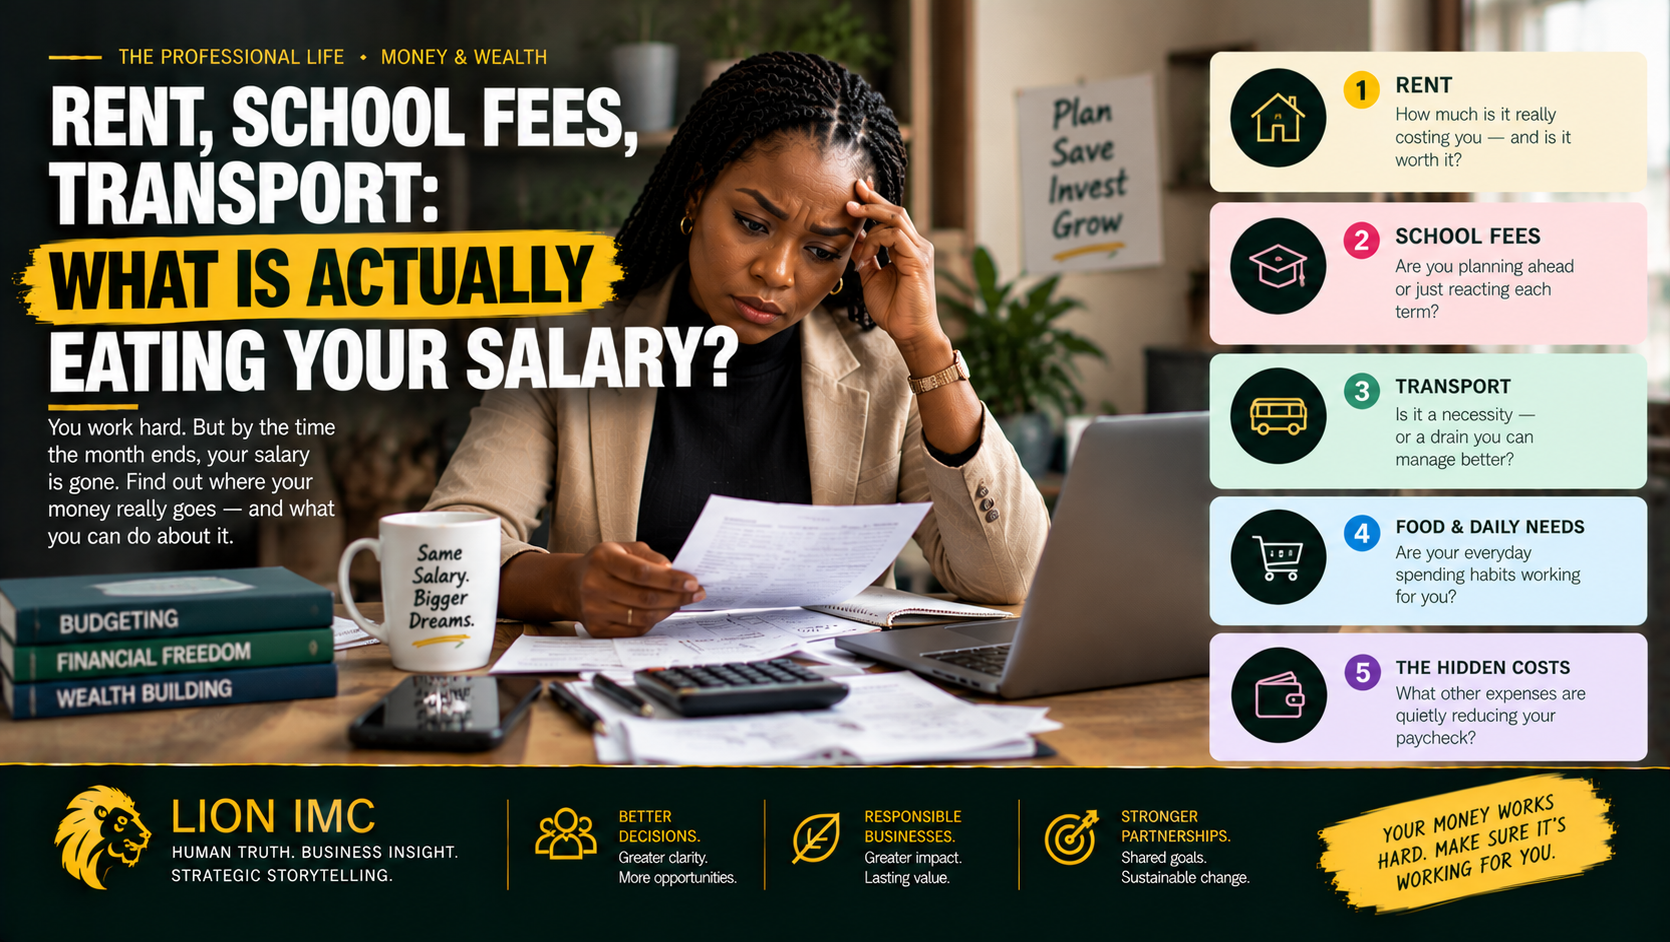


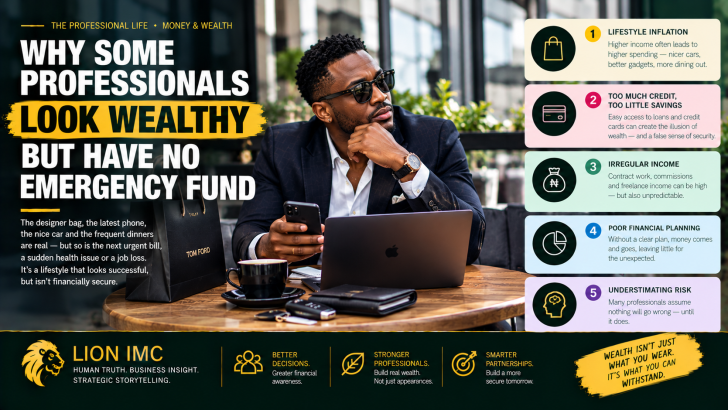
A professional can earn a respectable salary, dress well, drive a good car, live in a desirable neighbourhood and still be one emergency away from financial trouble.
A delayed salary. A sudden medical bill. A job loss. A family crisis. A business opportunity that requires immediate cash.
When any of these arrives, the person who appears financially comfortable may discover that almost all their money is already committed.
The problem is not necessarily that the person earns too little. Sometimes, it is that the lifestyle has expanded to absorb the income, leaving little money available for the unexpected.
Looking wealthy and being financially secure are two different things.
1. Every salary increase comes with a more expensive lifestyle
Imagine a professional who earned ₦350,000 monthly a few years ago. They lived modestly, used public transport and saved whatever remained after paying essential bills.
Their career progresses. Their salary rises to ₦900,000. They upgrade their apartment, buy a car, replace their phone, eat out more often and take on additional commitments.
None of these decisions is automatically irresponsible. Higher income can reasonably support a better quality of life.
But what happens when spending rises almost as quickly as income?
The apartment costs more. The car introduces fuel, maintenance, insurance and other expenses. Dining out becomes routine. Family expectations increase. New subscriptions and purchases become part of everyday life.
The salary is higher, but the money available at the end of the month has barely changed.
This is lifestyle inflation: as income increases, spending rises too, sometimes leaving little room for savings.
The danger is that the professional may interpret a higher salary as evidence of financial progress without checking whether their financial resilience has improved.
A promotion should ideally create more options. If it only creates more expensive obligations, the person may be earning more without becoming meaningfully more secure.
2. We can see what people own, but not what they owe
A car tells you that someone has access to a car. It does not tell you whether they own it outright, are paying instalments or are struggling to meet the repayments.
Designer clothes do not reveal whether they were bought with savings, credit or borrowed money. A beautiful apartment says little about the tenant’s financial reserves.
This is why appearances can be misleading.
Two professionals may look equally successful while having very different financial positions.
One may have a modest lifestyle, manageable expenses and substantial savings. The other may have a more impressive lifestyle but owe money on several purchases and have almost nothing available for an emergency.
The visible possessions are only one part of the financial picture.
A more useful assessment considers income, debts, savings, assets, recurring commitments and the ability to meet unexpected expenses without borrowing.
Even a person’s net worth the value of what they own minus what they owe does not tell the whole story. Someone can own valuable property and still lack the accessible cash needed to pay an urgent bill.
Financial security is not just about what you own. It is also about what you can afford to handle when life stops following your plan.
3. Credit can make a stretched lifestyle look affordable
Credit allows people to acquire things before they have saved the full amount. Depending on the terms and the purpose, borrowing can be useful. But it can also conceal financial pressure.
A professional may be able to afford a monthly car payment while struggling to pay for an unexpected repair. Another may use credit to maintain a lifestyle that their regular income cannot comfortably sustain.
The problem becomes more serious when multiple obligations accumulate.
There is the loan repayment, the credit purchase, the informal borrowing from a friend and the money borrowed to cover a previous shortfall. Each commitment reduces the income available for future expenses.
Then an emergency arrives.
Instead of using savings, the person takes another loan. The emergency is resolved, but the financial burden grows because interest and fees may increase the total cost.
Research by the US Consumer Financial Protection Bureau has documented the relationship between emergency savings, debt profiles and consumers’ ability to meet financial obligations. Its findings also recognise that people facing insufficient income and heavy obligatory expenses may struggle to build savings in the first place. These findings are useful for understanding the relationship between savings and resilience, though they should not be treated as statistics about Nigerian professionals specifically.
Credit is not the enemy. Depending on credit to fund ordinary living costs because income cannot cover them is a warning sign.
4. Family responsibilities can absorb the money nobody sees
For many Nigerian professionals, financial responsibilities extend beyond personal expenses.
There may be school fees, rent, household bills, support for parents, assistance to siblings, medical expenses for relatives and contributions to important family events.
These obligations can be meaningful and legitimate. Supporting family is not automatically poor financial management.
But when every available naira is allocated to someone or something else, the person providing the support may have no financial protection of their own.
A professional might save for a few months, then use the money to settle a relative’s urgent need. Another may feel unable to decline requests because their visible lifestyle creates the impression that they have more money than they actually do.
The result can be a difficult cycle: earn, spend, help others, run short and wait for the next salary.
The solution is not necessarily to stop supporting people. It is to recognise that the person providing support also needs a financial safety net.
Family assistance can be included in a budget, with a realistic amount allocated to it. An emergency fund should also be protected for genuine emergencies affecting the household, including the person who earns the income.
You cannot sustainably support everyone else if one unexpected event can destabilise your entire financial life.
5. Irregular income makes appearances especially unreliable
Not every professional receives a fixed salary every month.
Consultants, freelancers, entrepreneurs, commission-based workers and business owners may earn substantial amounts during good periods and much less during quiet ones.
A large payment can create the impression of prosperity. But if that payment must cover several months of personal expenses, business costs, tax obligations and outstanding commitments, the money may already have a purpose.
Consider a consultant who receives ₦3 million from a project. It may appear to be a windfall, but the consultant still needs to account for business expenses, future operating costs, personal bills and the possibility of a long gap before the next contract.
Spending as though the entire amount is disposable income can leave the consultant exposed when work slows down.
For people with variable earnings, financial planning should account for both the size and the timing of income. Strong months need to help carry weaker months.
The same principle applies to bonuses, commissions, business profits and large one-off payments. A good month is not always evidence that the next few months will be equally good.
6. An emergency fund is different from an investment portfolio
Some professionals believe they are financially prepared because they have investments, property or money committed to a business.
Those assets can contribute to long-term wealth. But they may not be immediately available when cash is urgently needed.
Selling property takes time. Liquidating an investment may involve delays, transaction costs or the risk of selling at an unfavourable moment. Money invested in a business may be needed to keep that business operating.
An emergency fund serves a different purpose.
It is money deliberately kept accessible for unexpected expenses or disruptions, such as an urgent medical bill, a major repair or the loss of income. The Consumer Financial Protection Bureau recommends keeping emergency savings somewhere safe and accessible, separate from money intended for other goals.
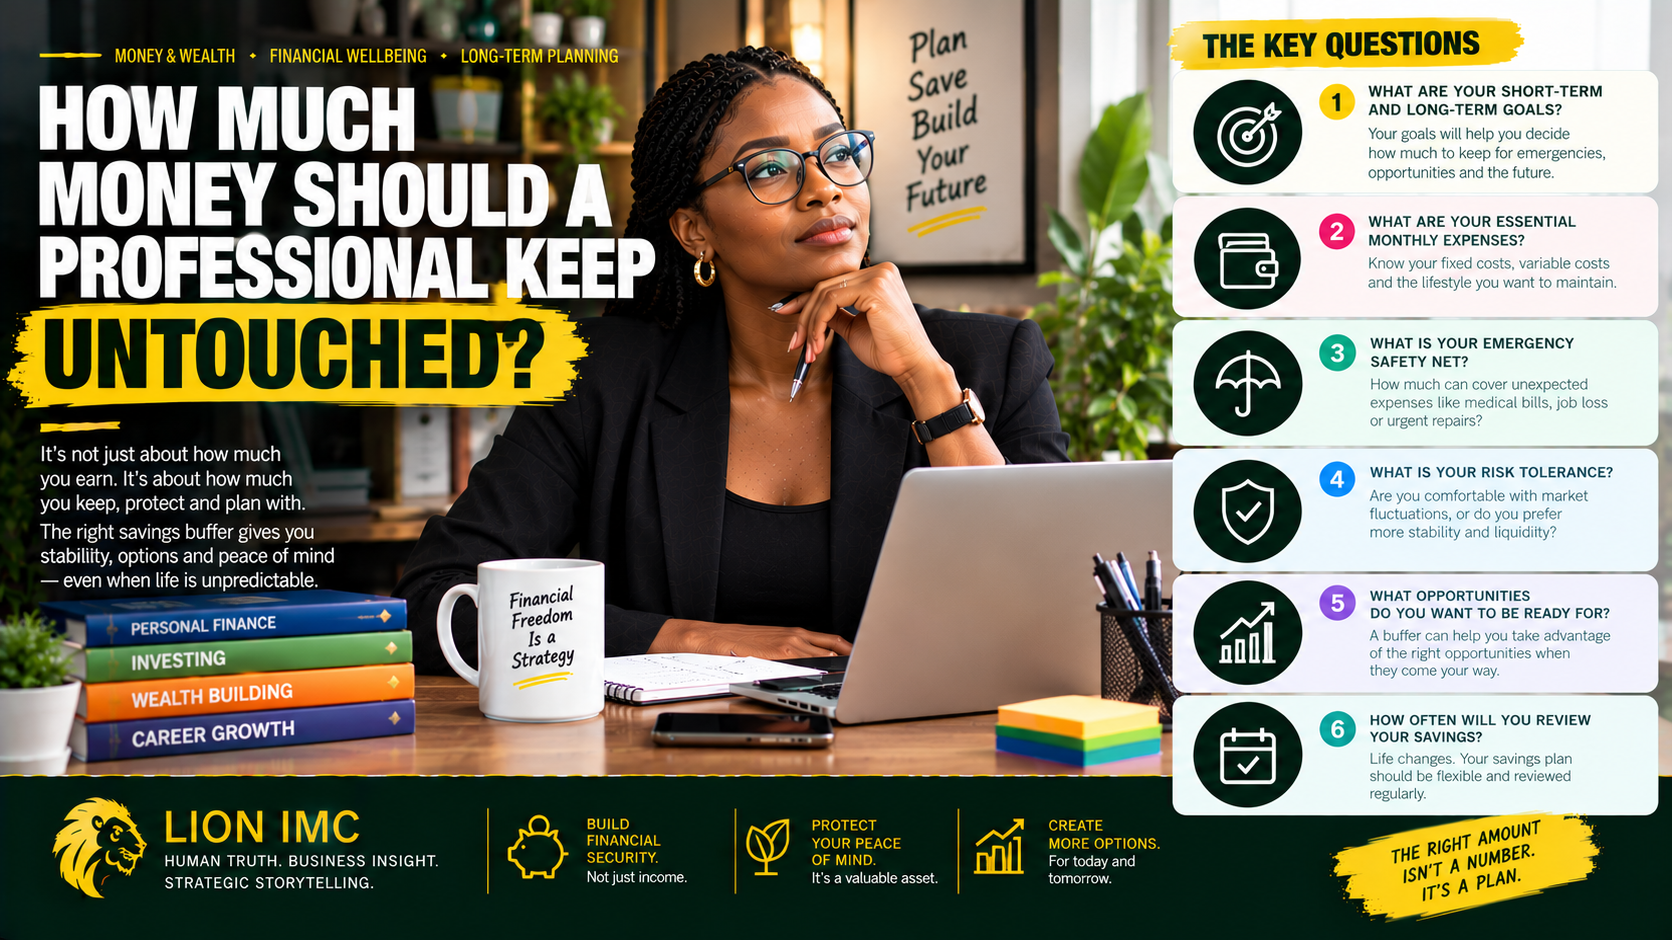
The amount required depends on personal circumstances. A professional with dependants, debt and irregular income may need a larger cushion than someone with stable income, low fixed costs and fewer financial responsibilities.
A common planning goal is to build towards several months of essential expenses. Three to six months is often used as a benchmark, but it is not a universal rule or a sum everyone can accumulate immediately.
If money is tight, starting with a smaller reserve is still useful. The first goal may be enough to handle a modest emergency without borrowing. The fund can then grow over time.
7. The real status symbol may be having options
There is nothing wrong with enjoying a good salary. Professionals should be able to benefit from their hard work, buy things they value and improve their standard of living.
The problem is not looking successful. It is building a life in which maintaining the appearance of success takes priority over being able to withstand financial shocks.
A person with an emergency fund has options. They may be able to leave an unsuitable job without accepting the first available offer. They may be able to repair a car without taking an expensive loan. They may be able to handle a family emergency without immediately selling an asset.
That does not mean savings can solve every crisis. A prolonged loss of income or major medical expense can overwhelm even a carefully built reserve. But a financial cushion can reduce the need to make desperate decisions under pressure.
A professional can enjoy good clothes, a comfortable home and a reliable car while also building financial security. These goals do not have to compete indefinitely.
The important thing is to ensure that spending decisions do not consume every opportunity to prepare for the future.
How to build an emergency fund without abandoning your lifestyle
Start with your essential monthly expenses: housing, food, utilities, transport, healthcare, debt obligations and the needs of dependants.
Then take five practical steps.
- Choose an initial target. Start with a manageable amount that could cover a realistic unexpected expense.
- Automate a contribution where possible. Move a portion of your income into a dedicated savings account when you are paid, rather than relying only on whatever remains.
- Save part of irregular income. Bonuses, commissions and strong business months can help build the reserve, provided immediate obligations are covered.
- Review lifestyle commitments. Identify recurring costs that leave you with little room to save. You do not need to eliminate every pleasure; prioritise the changes that make the biggest difference.
- Define what counts as an emergency. Use the fund for genuine unexpected needs or serious disruptions, not routine expenses that should already be in the monthly budget.
If your income is insufficient to cover essential expenses, do not treat the absence of savings as a personal failure. Focus on the most urgent financial pressures and explore what can realistically change. Building a reserve may need to happen gradually.
The objective is not to accumulate savings at any cost. It is to create a financial buffer that makes your life more resilient.
The question behind the appearance
A professional may look wealthy because their income supports an expensive lifestyle. Another may look ordinary while quietly building savings, reducing debt and investing for the future.
Neither appearance tells the complete story.
But if your lifestyle depends on every salary arriving on time, every client paying promptly and nothing unexpected happening, your financial position may be more fragile than it looks.
The real test of financial progress is not simply whether you can afford the life you live today. It is whether you can withstand a disruption without your entire life falling apart.
THE LION TAKE
Wealth is not only the ability to buy what you want. It is also the ability to handle what you did not plan for.
THE BIG QUESTION
If your salary or business income stopped today, how long could you maintain your essential expenses without borrowing or selling something important?