

A loan can help you buy a home, finance an education, grow a business or manage an emergency. But before you accept the money, understand what it will cost, how you will repay it and what happens if your circumstances change.
The loan offer arrives just when you need it.
Perhaps your car has broken down. Perhaps your rent is due. Perhaps you have found a business opportunity that requires more capital than you currently have. Or perhaps you want to buy a house, pay for a professional qualification or consolidate existing debts.
The lender says you qualify. The amount looks attractive. The monthly repayment appears manageable.
You begin thinking about what the money will solve.
But before you accept, there is another calculation worth making.
What will this loan demand from your future income?
A loan does not simply give you money today. It commits part of your future earnings to a decision you are making now.
That commitment may be worthwhile. Borrowing can help someone acquire an asset, fund a productive business or spread a major expense over time. But a loan can also leave a professional with less money to meet everyday needs, save for emergencies or respond to opportunities later.
In Nigeria, where professionals may already be managing rent, transport, family obligations, school fees and unpredictable expenses, the difference between a useful loan and a damaging one can come down to the details people overlook before signing.
The first principle is simple: do not judge a loan only by how much you will receive. Judge it by everything you must give back.
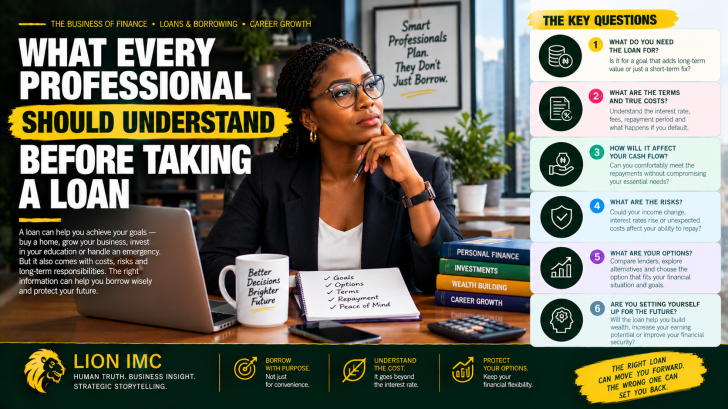
1. Know exactly why you are borrowing
Before comparing lenders, be honest about what the loan is supposed to achieve.
Are you borrowing to purchase an income-generating asset, finance an education, manage an emergency, consolidate expensive debt or pay for something you want but cannot currently afford?
The purpose matters because different loans create different financial consequences.
A loan used to purchase equipment for a business may help generate additional income. A loan for a professional qualification may improve your future opportunities, although the outcome is not guaranteed. A loan for an emergency may be necessary even if it produces no financial return.
Borrowing to maintain a lifestyle that your regular income cannot support is a different proposition.
Ask yourself:
- Is this expense essential, productive or discretionary?
- Is borrowing the only realistic option?
- Can I delay the purchase, save towards it or choose a cheaper alternative?
- Will the benefit last longer than the repayment period?
- Am I borrowing because I have a plan, or because I am under pressure?
You do not need to justify every loan by proving it will generate profit. But you should understand what you expect the money to accomplish.
2. The interest rate is not the whole cost
This is one of the most important distinctions in borrowing.
A lender may advertise an interest rate that sounds affordable while also charging processing fees, insurance premiums or other costs. Some loans may have penalties for late payment or early settlement, depending on the contract.
You need to know the total amount you will repay, not just the advertised rate.
Consider this simplified illustration:
Illustrative loan example
₦500,000
Assume a 12-month loan with a total interest charge of ₦100,000 and fees of ₦15,000.
Principal borrowed
₦500,000
Interest
₦100,000
Fees
₦15,000
Total repayment
Before any additional charges
₦615,000
Simple average over 12 months
₦51,250/month
These figures are hypothetical, not a current lender offer. The actual instalment schedule will depend on how the lender calculates interest and fees.
A loan advertised as “3% interest” also needs context. Is that 3% per month or per year? Is it calculated on the original principal or on the outstanding balance? Are fees additional? Does the amount quoted include compulsory insurance?
Those details can materially change the cost.
Before signing, request a written repayment schedule showing the principal, interest, fees, instalment dates and total amount payable. For digital consumer loans in Nigeria, the FCCPC’s 2025 lending regulations require covered lenders to disclose interest rates, fees and repayment schedules clearly.
3. Check whether your income can carry the repayment
A lender approving your application does not necessarily mean the loan is comfortable for your budget.
The lender assesses the application using its own criteria. You must assess the loan against your actual living expenses and responsibilities.
Suppose you take home ₦700,000 a month. After rent provisions, food, transport, family support, utilities, existing debt and other essentials, you have ₦120,000 left.
A new monthly repayment of ₦100,000 might technically fit your current budget. But it would leave only ₦20,000 for unexpected expenses, extra costs or savings.
One medical bill or transport problem could put you under pressure.
Instead of asking only whether you can make the instalment in a normal month, ask whether you can still manage if your expenses rise or your income falls.
A practical check is to write down:
- Your dependable monthly take-home income.
- Essential living costs and family obligations.
- Existing debt repayments.
- The proposed new instalment.
- A reasonable allowance for irregular expenses and emergencies.
If the repayment leaves almost no flexibility, the loan may be too large or too expensive for your present circumstances.
There is no single repayment-to-income percentage that guarantees safety for every professional. A salaried employee with stable income and few dependants may have a very different capacity from a freelancer with fluctuating earnings or a parent supporting an extended family.
A repayment is affordable when it fits your real financial life not merely when the lender says you qualify.
4. Understand what happens if you cannot pay on time
Before taking a loan, find out what the agreement says about late payments, default and missed instalments.
Ask:
- Is there a late-payment fee or default interest?
- Can the lender demand early repayment of the outstanding balance?
- Is a guarantor involved, and what obligations would that person assume?
- Is collateral required, and what could happen to it?
- How might a missed payment affect your credit history?
- Is there a process for discussing repayment difficulties?
Do not assume that a lender will automatically extend your deadline because you explain your circumstances. Any restructuring or payment arrangement should be confirmed with the lender.
It is also important to understand the difference between a legitimate recovery process and abusive conduct. Nigeria’s FCCPC has introduced rules addressing unfair digital lending practices, including privacy violations and abusive debt collection. It advises consumers to check the public register of approved digital lenders and understand the terms before borrowing.
If you are considering a digital loan, verify the lender’s current status through the FCCPC’s official digital lending register. Do not assume an app is legitimate simply because it appears in an app store or advertises fast approval.
5. Ask whether the repayment period makes sense
A longer repayment period can reduce the amount due each month. But it may increase the total interest paid over the life of the loan.
A shorter period may reduce total borrowing costs under some loan structures, but the larger instalments can strain your monthly budget.
The right balance depends on the loan’s cost, the purpose of the borrowing and how predictable your income is.
For example, financing a long-lasting asset may justify a different repayment period from borrowing to cover routine consumption. A business loan should also be assessed against the timing and uncertainty of the business’s cash flow.
Be careful about taking a long-term loan for something that will lose its value quickly, or borrowing for a short-term expense at a cost that will burden you long after the expense has passed.
Compare more than the monthly instalment. Compare the total repayment, duration and flexibility together.
6. Do not use one loan to hide another problem
Debt consolidation can sometimes simplify repayments or reduce borrowing costs. But taking a new loan to settle existing debt is only helpful if the new arrangement improves your overall position.
If the new loan has higher fees, a longer repayment period or a greater total cost, it may simply move the problem elsewhere.
Likewise, borrowing every month to cover a persistent gap between income and essential expenses may provide temporary relief without solving the underlying shortfall.
That does not mean people should never borrow to meet urgent needs. Sometimes there are few realistic alternatives.
It means you should identify what happens after the new loan is spent.
Will your income be sufficient to cover next month’s essentials and the new repayment? If not, what will change? If nothing changes, will you need another loan?
A cycle in which new borrowing pays for old borrowing can become difficult to escape.
7. Compare lenders—and read the agreement yourself
Do not accept the first offer simply because the lender has approved you quickly.
Where possible, compare offers from more than one credible lender. Look at:
| What to compare | Why it matters |
| Total repayment | Shows what the borrowing will cost overall |
| Interest calculation | Helps explain how the charge is determined |
| Fees and compulsory charges | Reveals costs beyond interest |
| Repayment schedule | Shows when money will leave your account |
| Late-payment terms | Helps you understand the consequences of missing a payment |
| Early repayment conditions | Establishes whether paying off the loan sooner has costs or benefits |
| Collateral and guarantees | Shows what assets or other people may be exposed to risk |
| Lender’s status | Helps you verify the provider and the applicable regulatory framework |
Read the agreement before accepting the funds. Keep a copy of the contract, repayment schedule and payment receipts.
If a clause is unclear, ask for an explanation in writing. If you believe a lender has breached your consumer rights, first raise the complaint with the provider; if it is not resolved, the FCCPC provides an official consumer complaint channel.
8. Consider what the loan prevents you from doing
Every repayment reduces the amount of income available for something else.
That may mean delaying an investment, reducing savings, postponing a course, taking fewer business risks or having less flexibility to change jobs.
This is the opportunity cost of borrowing.
A loan may still be worth taking if the benefit outweighs what you give up. But you should consider the alternatives before committing future income.
Ask yourself what you could achieve if you waited six months, borrowed a smaller amount, saved a deposit or chose a less expensive option.
You should also consider whether the loan could limit your ability to respond to a new opportunity. A repayment that is comfortable today may become restrictive if you want to relocate, start a business or take a lower-paying role that offers long-term career growth.
Borrowing is not only a question of whether you can afford the repayment. It is also a question of how much flexibility you are willing to exchange for the benefit you receive now.
The loan-readiness checklist
Before you sign, make sure you can answer these questions confidently.
Before you borrow
0 of 6 checked
I know exactly what the loan is for and why borrowing makes sense.
I understand the interest calculation, fees and total repayment.
I have checked the instalment against my real monthly budget.
I know what happens if I miss a payment or my income changes.
I have compared alternatives and, where possible, other credible lenders.
I have read the agreement and verified the lender’s status where applicable.
THE LION TAKE
A loan gives you access to money today in exchange for a claim on part of your future income. Make sure you understand that exchange before you agree to it.
Borrow when the purpose is clear, the terms are understood and the repayment fits your circumstances. Be cautious when the offer depends on urgency, hides the real cost or leaves you with no room for life’s ordinary surprises.
The goal is not to avoid borrowing at all costs. It is to avoid making a financial commitment whose consequences you have not fully considered.
Because the most important question is not simply, “Can I get this loan?”
It is: “After I take it, will I still have the financial room to live, respond and move forward?”
THE BIG QUESTION
What do you think matters most before taking a loan: the interest rate, the monthly repayment, the total cost or the reason you need to borrow in the first place?