

Hmm…we should resist the predictable “put ₦3m here, ₦2m there” personal-finance article.
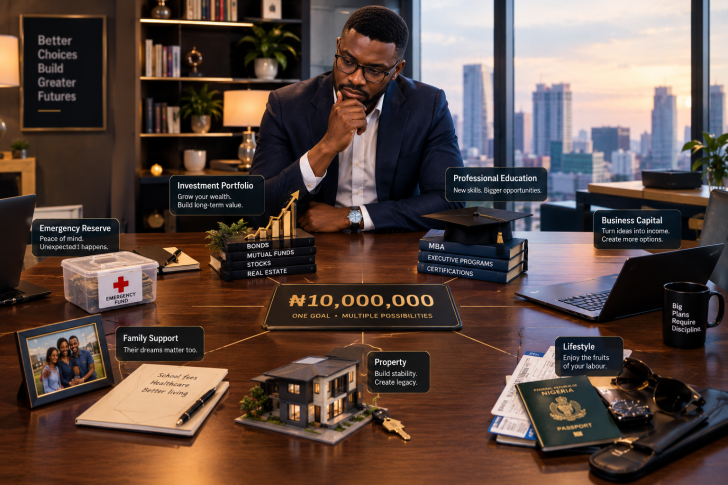
The more interesting question is: what is the first ₦10 million supposed to accomplish?
Because for many professionals, the first meaningful lump sum is not really an investment problem. It is a life-architecture problem. Do you use it to buy status, solve old problems, create breathing room, protect yourself from your next emergency, or finally make your money start working?
The Lion’s take? Your first ₦10m should buy you options before it buys you things.
The first serious money you accumulate can either make your life look richer or make your life genuinely more secure.
There is something psychologically different about the first ₦10 million.
It is no longer just salary.
It feels like money.
Enough to make you start imagining things you could not previously afford.
A car.
A plot of land.
A better apartment.
A business.
A foreign trip.
A new phone.
A bigger lifestyle.
An investment.
Or perhaps the thing you have secretly wanted for years.
And that is precisely why the first ₦10 million can be dangerous.
Because the moment you finally have meaningful money, everybody — including you — starts asking what you should do with it.
The investment salesperson has an answer.
The property agent has an answer.
The car dealer has an answer.
Your friends have an answer.
Your family may have several.
But before you ask:
“What should I buy with ₦10 million?”
there may be a better question.
“What should ₦10 million change about my life?”
MONEY HAS JOBS TOO
We often talk about money as if every naira should be invested.
It shouldn’t.
Some money needs to protect you.
Some needs to grow.
Some needs to remain accessible.
Some may legitimately be used to improve your life.
And some should probably do nothing for a while except give you breathing space.
The mistake is treating all ₦10 million as one pot with one purpose.
It isn’t.
It can have several jobs.
The first is perhaps the least glamorous:
keeping you from becoming desperate.
FIRST, BUY YOURSELF SOME BREATHING ROOM
Imagine losing your job one month after receiving ₦10 million.
If you have rent due, school fees approaching, dependants, debt and no emergency reserve, the money suddenly looks much smaller.
This is why liquidity matters.
An emergency reserve is not money that failed to make a return.
It is money that bought you time.
Time to look for another job without accepting the first terrible offer.
Time to recover from an emergency.
Time to handle an unexpected medical expense.
Time to survive a business setback.
Time to make a rational decision instead of an urgent one.
For a professional, that can be enormously valuable.
Financial security is partly the ability to make decisions without panic.
THEN ASK: WHAT DEBT IS EATING YOUR FUTURE?
A person with ₦10 million in savings and expensive debt may not actually have ₦10 million of wealth.
They may have ₦10 million sitting in one account while another part of their financial life is quietly charging them for the privilege.
This is why the first serious lump sum should trigger a debt audit.
Not every debt should automatically be paid off immediately.
Some debt may be relatively cheap.
Some may finance an asset or business.
Some may have contractual consequences.
But high-cost consumer debt deserves serious attention because it can consume future income before that income arrives.
There is little point trying to make your money work for you while expensive debt is working against you.
DO NOT LET ₦10 MILLION TURN INTO A MORE EXPENSIVE LIFESTYLE
This may be the most important trap.
You receive your first major financial windfall.
Then your life quietly upgrades.
The car becomes more expensive.
The apartment becomes more expensive.
Restaurants become more frequent.
The phone gets upgraded.
You start travelling differently.
Family expectations change.
And suddenly the ₦10 million has not created wealth.
It has created a more expensive version of you.
Lifestyle inflation is particularly dangerous because it does not feel like financial irresponsibility.
You are not necessarily gambling the money away.
You are simply making tomorrow’s expenses larger.
The money disappears gradually.
And the salary that once felt adequate suddenly feels inadequate.
A financial breakthrough should not automatically become a lifestyle breakthrough.
YOUR FIRST ₦10 MILLION SHOULD BUY YOU OPTIONS
This is where the conversation becomes more interesting.
Imagine that your ₦10 million allows you to say:
“I don’t have to stay in a terrible job simply because I cannot survive three months without salary.”
Or:
“I can take six months to build a serious business.”
Or:
“I can pay for training that materially changes my earning capacity.”
Or:
“I can move closer to the kind of work I want.”
Or:
“I can survive an unexpected family emergency without selling everything.”
That money has done something more valuable than simply earning interest.
It has increased your options.
And options are a form of wealth.
SOME OF THE MONEY SHOULD MAKE YOU MORE EARNABLE
This is where professionals sometimes make an interesting mistake.
They invest heavily in financial assets while neglecting the asset that produces their income:
themselves.
A professional’s earning power can be an enormous asset.
A qualification.
A specialist skill.
Technology.
A professional certification.
A better portfolio.
A business capability.
A new language.
Sales ability.
Leadership development.
Digital expertise.
International-market capability.
A serious professional network.
But there is a warning here.
Don’t spend ₦2 million on a course because somebody promised that it will “change your life.”
The test should be harder:
What specific economic capability will this money help me build?
If the answer is unclear, the expense deserves another look.
THEN LET SOME OF THE MONEY BECOME CAPITAL
At some point, money needs to stop being merely defensive.
It needs to become productive.
That could mean appropriately selected investments, business capital, or other assets suited to your circumstances, risk tolerance, time horizon and financial goals.
But this is where the first ₦10 million should not become an invitation to chase whatever investment is currently trending.
Nigeria’s financial environment makes understanding liquidity, risk and institutional safety especially important.
For example, the Nigeria Deposit Insurance Corporation currently provides deposit insurance coverage of up to ₦5 million for depositors in Deposit Money Banks, subject to the scheme’s rules. That is protection against the failure of an insured institution; it is not the same thing as saying every financial product or investment is risk-free.
And monetary conditions matter too. As of September 22, 2026, the Central Bank of Nigeria’s Monetary Policy Committee set the Monetary Policy Rate at 23%. That does not tell an individual exactly where to put money, but it illustrates why the financial environment should be considered when evaluating cash, fixed-income products and other investments.
The lesson is simple:
Do not invest ₦10 million simply because somebody says the return is attractive. Understand what you are buying, how liquid it is, what can make you lose money and who regulates or protects the institution involved.
SHOULD YOU BUY LAND?
Maybe.
But “I have ₦10 million, therefore I must buy land” is not an investment strategy.
Property can be useful.
It can appreciate.
It can generate rental income.
It can satisfy a long-term housing goal.
But property can also be illiquid, expensive to transact, difficult to verify and expensive to maintain.
And there is a very important question:
Why are you buying it?
For your own future home?
Long-term wealth?
Rental income?
Speculation?
Because everybody around you is buying plots?
Those are different objectives.
Do not let the emotional satisfaction of saying “I own land” substitute for knowing what the asset is supposed to accomplish.
SHOULD YOU BUY A CAR?
If your current car is unreliable and transport is damaging your ability to work, perhaps a vehicle can have genuine economic value.
But a car is rarely an investment simply because you paid a lot for it.
It consumes money.
Fuel.
Maintenance.
Insurance.
Repairs.
Depreciation.
Registration.
Parking.
And sometimes an impressive monthly lifestyle.
So if your first ₦10 million becomes a ₦9 million car, you may have acquired something valuable to your lifestyle.
You have not necessarily built financial security.
There is a difference.
SHOULD YOU START A BUSINESS?
Again:
Maybe.
But the first serious money a person accumulates is often when they suddenly become vulnerable to entrepreneurial fantasies.
Someone tells you:
“Put ₦5 million into this business. The returns are huge.”
You hear:
“₦5 million can become ₦20 million.”
What you may not hear is:
“You could also lose ₦5 million.”
Business capital should come with an actual business model.
Who pays?
Why?
How much does it cost to acquire customers?
What are the margins?
How quickly does cash come back?
What happens if sales are 50% lower than expected?
What happens if the founder cannot work for three months?
What is the exit?
The first ₦10 million is too important to use as tuition for a business idea that has never survived contact with reality.
AND THEN THERE IS FAMILY
This is where financial planning becomes deeply Nigerian.
Your first serious money may not belong emotionally to you alone.
Someone may need school fees.
A parent may need support.
A sibling may have a business idea.
Someone may expect assistance with rent.
A relative may hear that you have “made money.”
And because you are now the person with money, the requests may multiply.
Generosity is not a financial mistake.
But unplanned generosity can become one.
If you give away money, know what you are giving.
Is it support?
A gift?
A loan?
An investment?
An emergency contribution?
Those are different things.
If you cannot afford to lose the money, don’t call it a loan simply because you are uncomfortable calling it a gift.
YOUR FIRST ₦10 MILLION SHOULD ALSO BUY YOU SOMETHING NOBODY CAN SEE
Peace.
Not permanent peace.
Not a life without problems.
But the knowledge that one unexpected event does not automatically destroy you.
That you can survive a period without income.
That one medical bill will not force you to sell your investments.
That you can say no to a bad opportunity.
That you can leave a toxic situation.
That you can wait for the right opportunity.
That you can take a calculated risk.
That you have not converted every naira into something that cannot easily be recovered.
Money becomes powerful when it gives you choices.
SO HOW MIGHT THE ₦10 MILLION BE THINKING?
Not as a rigid formula.
Not as “put exactly X% here.”
But as a set of jobs.
- PROTECT
Emergency reserve and immediate financial vulnerabilities.
- CLEAN UP
Expensive debt and financial obligations that are quietly consuming future income.
- BUILD
Skills, tools, credentials or capabilities that can increase future earning power.
- GROW
Appropriately researched investments and productive assets.
- CREATE
Business or income-producing opportunities where the economics genuinely make sense.
- LIVE
A reasonable amount can improve your quality of life.
- GIVE
If supporting family or causes matters to you, give deliberately rather than emotionally committing money you cannot afford to lose.
That is not a ₦10 million formula.
It is a ₦10 million philosophy.
THE REAL TEST IS NOT HOW MUCH YOU HAVE AFTER SPENDING IT
It is what your life looks like afterwards.
Suppose you had ₦10 million and five years later:
You have no savings.
No investment.
No new earning capability.
No asset.
More expensive habits.
And the same financial anxiety.
Then the money passed through your life.
It did not transform it.
But imagine another outcome.
You have an emergency reserve.
Your expensive debt is gone.
Your earning capacity has increased.
Some money is invested.
You own productive assets.
You have a stronger professional position.
Your lifestyle is better but still sustainable.
And you can survive several months without income.
That ₦10 million did something.
It changed your financial architecture.
THE LION TAKE
Your first ₦10 million should not be judged by how expensive it makes you look.
It should be judged by how much more difficult it becomes for life to financially break you.
It should buy you:
time.
options.
earning power.
protection.
productive assets.
breathing room.
And, eventually, freedom.
Because the first serious money you accumulate has a very important job.
It should help make sure that the next serious money you accumulate is easier to keep.
Don’t ask only, “What can ₦10 million buy me?”
Ask:
“What can ₦10 million make possible for the person I am becoming?”