

In Nigeria, the above question can feel particularly personal. By your late thirties, relatives may be asking when you intend to build your own house. Friends may be sharing pictures of newly completed homes. Colleagues may be buying land, paying developers in instalments or celebrating their first property purchase.
And if you are still renting, it can begin to feel as though you are falling behind.
But turning 40 is not a financial deadline. The better question is whether you can afford to buy a home without compromising the life you are trying to build.
1. The pressure to own before 40 is real but it is not a financial plan
In many Nigerian families, owning a house is treated as proof that adulthood has been achieved. Marriage, children, career advancement and homeownership can become a single checklist, with 40 serving as an unofficial deadline.
The pressure can push people into decisions that look impressive from the outside but feel burdensome in private.
Someone might buy land they cannot develop for years, commit to a property far from their workplace, exhaust their savings on a building project or take on repayments that leave little room for emergencies.
There is nothing wrong with wanting a home. The danger lies in allowing a birthday or other people’s expectations to determine the timing.
A house should serve your life. Your life should not become an endless struggle to pay for a house you bought to prove that you had made it.
2. A house is an asset but it is not automatically a good investment
Property can provide security, build equity and potentially appreciate in value. It can also become expensive to maintain, difficult to sell quickly or less profitable than expected.
The outcome depends on the purchase price, location, financing, property condition, holding period and what else you could have done with the money.
The common argument that renting is simply throwing money away misses an important point: rent pays for somewhere to live, while ownership comes with additional costs and responsibilities.
A homeowner may have to pay for repairs, security, service charges, insurance where applicable, taxes and legal or administrative costs. A buyer who borrows also has to consider interest and repayment risk. The US Consumer Financial Protection Bureau’s guidance on buying versus renting makes the same general distinction: homeownership can build equity, but it is
There is another consideration. Money tied up in a house is not always readily available when you need it. A property may be valuable on paper, but it cannot necessarily pay tomorrow’s medical bill or replace lost income without being sold, rented out or used to secure financing.
Owning a house and being financially secure are not the same thing. Ideally, you work towards both.
3. What does buying a house really cost in Nigeria?
The advertised price is only the beginning.
Before committing to a property, calculate the full cost of acquiring and keeping it.
- Purchase price: The amount paid to the seller or developer.
- Legal and transaction costs: Fees for legal work, searches, documentation, registration and other applicable charges.
- Property verification: Independent checks on ownership, title, boundaries, approvals and any encumbrances.
- Financing: Deposit or equity contribution, interest, fees and the full repayment schedule if borrowing.
- Completion and furnishing: Finishing work, repairs, fittings, appliances and moving expenses.
- Ongoing ownership: Maintenance, security, estate charges, utilities and applicable property-related taxes or levies.
- Unexpected costs: Construction overruns, defects, delays or changes in personal circumstances.
The exact amounts vary by location, property type, transaction structure and financing arrangement. Get written estimates rather than relying solely on an agent’s assurance.
In particular, do not commit your entire financial reserve to the purchase. A home that leaves you unable to handle an emergency can turn a milestone into a source of vulnerability.
4. Can you afford the house or only the deposit?
This is one of the most important questions to answer honestly.
You may have enough savings to make an initial payment on a property without having enough income to sustain the purchase.
Consider a hypothetical professional who has saved ₦20 million towards a house. If the deposit, transaction expenses and immediate renovation work consume nearly all of it, the buyer may become financially exposed immediately after taking possession.
The decision should account for what remains after the purchase, not merely whether the initial payment is possible.
Ask yourself:
- Will I still have an emergency reserve after paying the deposit and transaction costs?
- Can my income comfortably cover repayments and normal living expenses?
- Can I continue saving for retirement, healthcare, children’s education or other priorities?
- What happens if my salary stops, my business loses revenue or a major repair becomes necessary?
- Am I depending on a future salary increase or an uncertain business deal to make the numbers work?
If the plan only works under perfect conditions, it may be too fragile.
5. Nigeria’s mortgage options deserve investigation
Many prospective buyers assume they must save the entire purchase price before they can own a home. Others assume a mortgage is automatically unaffordable.
Neither assumption should replace research into the options actually available to them.
Nigeria’s Ministry of Finance Incorporated Real Estate Investment Fund (MREIF) is one example of a housing-finance initiative worth investigating. In an August 2026 update, the State House reported that the programme had disbursed ₦140 billion through 21 financial institutions to create 2,018 mortgages across 27 states. The programme’s stated terms include a fixed interest rate of 9.75% annually for repayment periods of up to 20 years, with a minimum equity contribution of 10%, subject to eligibility and lender assessment.
These are reported programme terms, not a guarantee that every applicant will qualify or that every property is eligible. Prospective borrowers should confirm current requirements, participating institutions, fees and repayment obligations directly before making commitments.
Other possibilities may include employer-supported housing schemes, cooperative arrangements or structured payment plans from credible developers. Each option requires scrutiny of the actual contract and total cost.
A financing arrangement is only helpful if the repayments remain sustainable and the property and title are properly verified.
6. Sometimes, renting while building wealth is the smarter move
There is a persistent belief that every naira spent on rent is wasted. But renting can be a rational financial choice, particularly when your career, income or location is still changing.
Imagine two professionals in their thirties.
The first buys a property that absorbs most of their savings and leaves them with little flexibility. The second continues renting while building savings, investing within their risk tolerance and improving their earning capacity.
The second person has not necessarily made the better decision. That depends on rent, property prices, investment returns, the length of time they stay and many other factors. But neither has the first person automatically won simply by acquiring a house.
Renting may make sense if you expect to relocate, cannot comfortably fund ownership, need to preserve capital for a business or have not identified a property that suits your long-term plans.
Buying may make more sense if you have stable financing, can handle the full costs, expect to stay long enough to justify the commitment and value the security of having a home of your own.
The key is to compare realistic alternatives, not to assume one choice is always superior.
7. What if you are approaching 40 and still do not own a home?
First, separate your actual financial position from the embarrassment you may feel when comparing yourself with others.
A 38-year-old professional with strong savings, manageable obligations and a growing investment portfolio may be in a healthier financial position than a homeowner whose property is heavily financed and whose cash reserves are depleted.
Equally, a person who has spent years paying rent without saving anything may need to reconsider their financial plan. The answer is not to panic-buy a house, but to establish a realistic path towards greater housing security.
Start with your income, expenses, savings, debts and existing assets. Decide whether your immediate goal is to buy a completed home, acquire land, build gradually, explore a mortgage or continue renting while strengthening your finances.
Then establish a timeline based on what the numbers permit.
Turning 40 without owning a house is not proof of failure. But if homeownership matters to you, it is worth turning the aspiration into a specific plan rather than postponing it indefinitely.
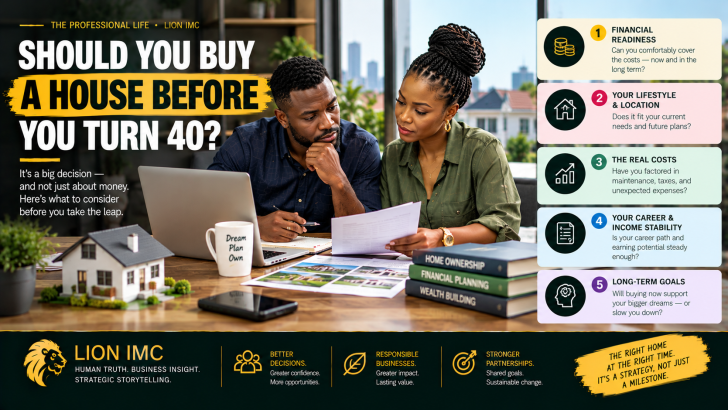
8. Five questions to answer before buying
Before signing any agreement or transferring money, consider these questions:
- Can I afford the complete cost? Include acquisition, financing, completion and ongoing expenses.
- Will I still have financial breathing room? Preserve resources for emergencies and other important goals.
- Does the location fit my life? Consider commuting, work opportunities, schools, healthcare, infrastructure and likely future needs.
- Have I independently verified the property? Use qualified legal and technical professionals to check title, documentation, boundaries, approvals and physical condition.
- Would I still choose this property without the pressure to own before 40? If the answer is no, reconsider the timing or the property itself.
The right home, at the right time
Buying a house before 40 can be a meaningful achievement. It can provide stability, independence and an asset that supports your long-term plans.
But it should not be treated as a compulsory milestone that overrides every other financial priority.
The better goal is not simply to become a homeowner as early as possible. It is to become a homeowner under conditions that allow you to enjoy the security you worked for.
Do not buy a house just to arrive at 40 with an address you own. Buy when the property, the financing and your wider financial life make sense together.
THE LION TAKE: A house is meant to provide security. Do not sacrifice all your financial security just to own one.
THE BIG QUESTION: If you turned 40 tomorrow, would you rather own a house with almost no savings left or still rent while having the financial freedom to make your next move?